How to Analyze a Cash Flow Statement: A Full Guide
To analyze a cash flow statement, read its three sections in order: operating, investing, and financing. Compare cash from operations with net income, then subtract capital spending to get free cash flow. Check the pattern of positive and negative totals, compare at least two years, and read the notes to learn why cash moved.
This guide explains each step with formulas, a worked example, and the mistakes that trip up beginners. It also shows how to do the analysis with AI when you have several years or several companies to compare.
What a cash flow statement tells you
The cash flow statement is one of the core financial statements, next to the balance sheet and the income statement. It tracks real money moving in and out of a business.
The US Securities and Exchange Commission (SEC) explains it in its Beginners' Guide to Financial Statements. It says these statements "report a company’s inflows and outflows of cash." That matters "because a company needs to have enough cash on hand to pay its expenses and purchase assets."
The SEC also draws the key contrast. An income statement "can tell you whether a company made a profit." A cash flow statement "can tell you whether the company generated cash." The two answers can differ for years.
Three more points from the SEC shape how you read it:
- It covers a period. It "shows changes over time rather than absolute dollar amounts at a point in time."
- It reuses other statements. It "uses and reorders the information from a company’s balance sheet and income statement."
- It ends with one number. The bottom line "shows the net increase or decrease in cash for the period."
Before you start: what you need
Gather these before you begin:
- At least two years of statements. Three to five years is better for spotting trends.
- The income statement and balance sheet for the same years. You will compare figures across all three.
- The notes to the financial statements. They explain large or unusual items.
- The management discussion (MD&A). It explains changes in cash in management's own words.
- A spreadsheet. Excel or Google Sheets is enough for the formulas below.
For a public US company, all of these sit in the annual report on Form 10-K. For your own business, export the statement from your accounting system.
Read the three sections
The SEC says these statements "are divided into three main parts." Each covers one type of activity.
Operating activities. This section starts from net income. The SEC says it "reconciles the net income (as shown on the income statement)" to the cash the business actually received or used. It adds back non-cash costs, such as depreciation. It also adjusts for changes in receivables, inventory, and payables.
Investing activities. This section covers long-term assets. The SEC lists "purchases or sales of long-term assets, such as property, plant and equipment, as well as investment securities." Buying machinery is a cash outflow here. Selling investments is an inflow.
Financing activities. This section covers money from and to owners and lenders. The SEC lists "cash raised by selling stocks and bonds or borrowing from banks" as typical sources. Repaying a loan, paying dividends, and buying back shares are uses of cash.
Add the three totals, and you get the net change in cash for the year. It should match the change in cash on the balance sheet.
Start with operating cash flow
Operating cash flow is the most important line on the cash flow statement. It shows whether the core business brings in cash on its own.
Compare it with net income from the income statement. A simple ratio helps:
Cash Conversion = Cash from Operations / Net Income
A ratio near or above 1.0 means profit is turning into cash. A ratio well below 1.0 for several years is a warning sign. It often means customers are paying more slowly or inventory is piling up.
Then look at the working capital lines inside the operating section:
- Accounts receivable up. Sales were booked but not yet collected.
- Inventory up. Cash went into goods that are not yet sold.
- Accounts payable up. The company is paying its suppliers more slowly, which holds on to cash for now.
A one-year swing can be normal, such as stocking up before a busy season. The same swing year after year deserves questions.
Calculate free cash flow
Free cash flow shows the cash left after the business pays to keep and grow its assets. Many analysts treat it as the cash that could go to owners or to paying down debt.
Free Cash Flow = Cash from Operations − Capital Expenditures
Capital expenditures usually appear in the investing section as purchases of property, plant, and equipment. The label varies by company.
Two related measures help with comparisons:
- Cash flow margin = Cash from Operations / Revenue. It shows how much cash each sales dollar brings in.
- Free cash flow margin = Free Cash Flow / Revenue. It shows the same after capital spending.
These are common analyst formulas, not GAAP totals, so companies may define them differently in their reports. Calculate them yourself from the cash flow statement so every year uses the same method.
Read the pattern of the three totals
The signs of the three section totals tell a quick story. Here are common patterns:
| Operating | Investing | Financing | What it often means |
|---|---|---|---|
| Positive | Negative | Negative | A mature business that funds its own investment and pays owners or lenders |
| Positive | Negative | Positive | A growing business that borrows or raises money to invest faster |
| Negative | Negative | Positive | A young or struggling business that relies on outside funding |
| Negative | Positive | Positive or negative | A business selling assets to cover cash needs |
A pattern is a starting point, not a verdict. A startup with negative operating cash flow may be on plan. A mature company with the same pattern needs a closer look.
Compare periods and connect the statements
One year of cash flow is a snapshot. Several years show the direction.
Put each year in its own column. Then check these points:
- Is operating cash flow growing with revenue? If revenue grows but operating cash flow does not, look at working capital.
- Is capital spending steady or rising? A jump may signal expansion, which can pay off later.
- How is investment funded? Compare free cash flow with dividends, buybacks, and new debt.
- Is cash rising because of the business or because of borrowing? The financing section answers this.
The SEC notes that cash flows are "related, but not equivalent, to net income shown on the income statement." It adds: "No one financial statement tells the complete story." Read our guides on how to analyze a balance sheet and how to analyze an income statement for the other two.
Red flags on a cash flow statement
Some patterns deserve a closer look before you trust the headline numbers. None of them proves a problem on its own. Each one is a reason to read the notes.
Profit up, operating cash down, for two years or more. One year can be timing. Two or more years often points to slow collections or rising inventory.
Payables stretched to prop up cash. A big jump in accounts payable lifts operating cash this year. Suppliers will want that money back, so the boost does not last.
Free cash flow below dividends. If a company pays out more than it generates, the gap comes from cash reserves or new debt.
Capital spending far below depreciation. Spending less than the assets wear out can lift free cash flow for a while. Over time it can leave equipment old and slow.
Large one-off inflows. Selling a building or a division brings in cash once. Remove it before you judge the business.
Cash from financing every year. Steady borrowing or share sales may be fine for a growing company. For a mature one, it may mean the business cannot fund itself.
Keep these checks next to your notes when you read each cash flow statement. They turn a page of totals into a short list of questions for management or your finance team.
How to analyze a cash flow statement with AI
The steps above are quick for one company and two years. They get slow with five years, several companies, or a stack of PDF reports. An AI tool can read the statements, calculate the ratios, and flag the changes.
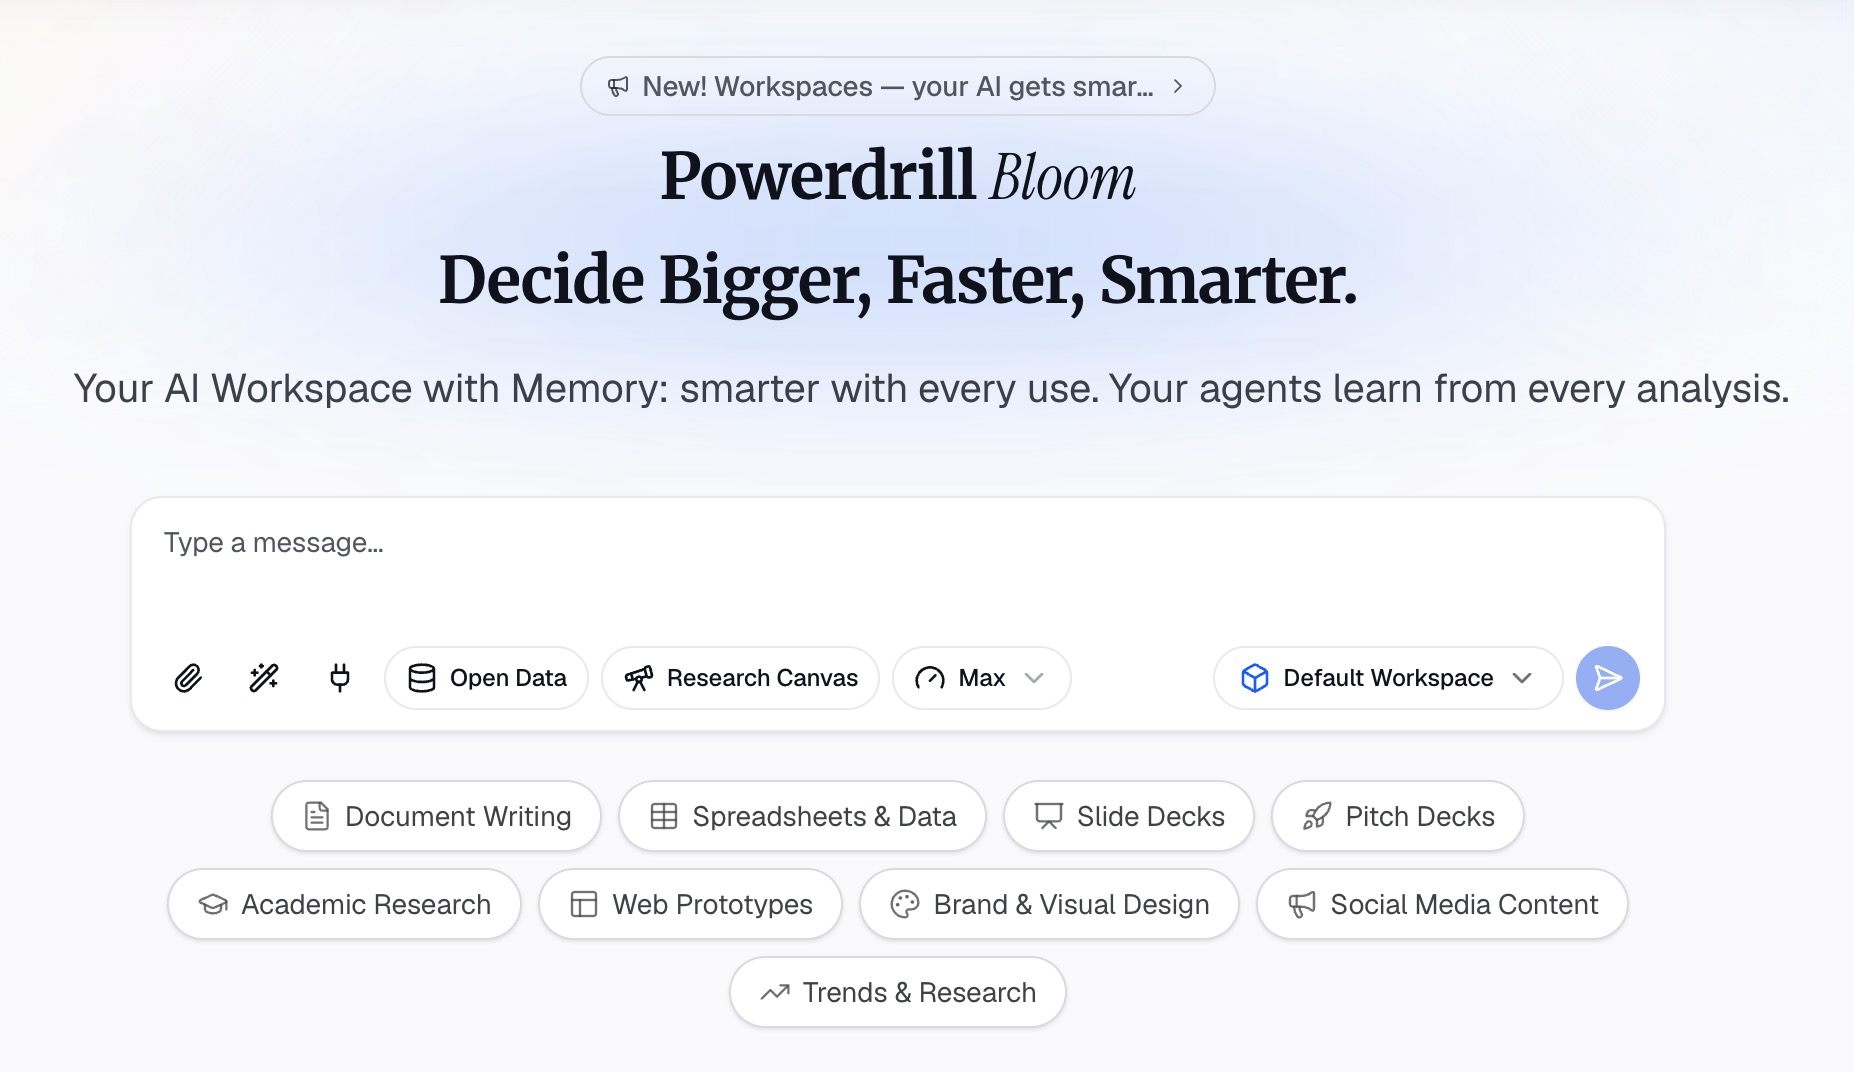
Here is the method in three steps, using Powerdrill Bloom.
Step 1: Upload or pull the statements
Upload the cash flow, income, and balance sheet reports you want to compare. They can be Excel exports from an accounting system or PDF annual reports.
The AI Financial Analysis Tool says it can "Run financial analysis on your P&L, balance sheet and cash flow." For a public company, the SEC Filing Search page covers "SEC filings, earnings, balance sheets, income statements, cash flows, dividends, and insider transactions."
Step 2: Ask for the ratios in natural language
Describe the analysis you want. For example: "For each year, show cash from operations, capital expenditures, free cash flow, and cash conversion. Explain the biggest changes in working capital."
The financial analysis page lets you "Pick the lens ratios, trends, anomalies or variance narrative." It also offers "Trend lines across periods with QoQ and YoY callouts."
Then ask follow-up questions, such as "How much of the investment was funded by new debt?"
Step 3: Check the figures and export the report
Check each result against the source statement. Pick two figures, such as cash from operations and capital expenditures, and confirm them by hand. The SEC Filing Search page says "Every answer is backed by SEC, with links to the original records."
Then export the analysis for review. For your own company's cash planning, the AI Cash Flow Analysis Tool covers runway and 13-week cash flow.
A worked example
Here is a short example for an invented company, Cedar Outdoor Gear. All figures below are invented and in thousands of dollars.
| Line item | Year 1 | Year 2 |
|---|---|---|
| Revenue | 10,000 | 12,000 |
| Net income | 1,200 | 1,500 |
| Depreciation | 400 | 450 |
| Change in working capital | -100 | -650 |
| Cash from operations | 1,500 | 1,300 |
| Capital expenditures | -600 | -900 |
| Free cash flow | 900 | 400 |
| Cash from financing | -300 | 200 |
| Net change in cash | 600 | 600 |
Now apply the steps.
Operating cash. Net income rose 25%, but cash from operations fell about 13%. Cash conversion dropped from 1.25 to about 0.87.
Working capital. Working capital absorbed 650 in Year 2, up from 100. The notes should show whether receivables or inventory drove it.
Free cash flow. Free cash flow fell from 900 to 400, down about 56%. Higher capital spending explains part of the drop.
Financing. In Year 1 the company paid out 300. In Year 2 it brought in 200, likely from new debt. Cash still rose by 600, but less of it came from the business.
The questions. Are customers paying more slowly? Was the extra inventory planned for a new season? Is the new capital spending expected to lift sales?
Common cash flow statement mistakes
Judging a company by net income alone. Profit can rise while cash falls. Always compare the two.
Ignoring working capital. Large swings in receivables and inventory explain most gaps between profit and cash.
Treating all negative cash flow as bad. Heavy investment shows up as an outflow. Check what the money bought.
Missing financing as the source of cash. A rising cash balance funded by debt is not the same as cash earned.
Comparing different definitions. Company-reported free cash flow may use its own method. Calculate it yourself from the statement.
Skipping the notes. One-off items, such as a large tax payment or a legal settlement, can distort a single year.
For the wider workflow, see our guide on analyzing financial data with AI.
Want to run these ratios on your own reports? Try Powerdrill Bloom with two years of statements, and ask for free cash flow and cash conversion by year.
Frequently asked questions
How do you analyze a cash flow statement?
Read the operating, investing, and financing sections in order. Compare cash from operations with net income, then subtract capital expenditures to get free cash flow. Check the pattern of the three totals, compare several years, and read the notes for large changes.
What are the three sections of a cash flow statement?
The three sections are operating, investing, and financing activities. Operating covers cash from the core business. Investing covers long-term assets and investment securities. Financing covers money raised from or returned to owners and lenders.
How do you calculate free cash flow?
Free cash flow is cash from operations minus capital expenditures. Find cash from operations at the end of the operating section. Capital expenditures usually appear in the investing section as purchases of property, plant, and equipment.
What is a good cash flow from operations?
There is no single good number. A useful check is cash conversion, which divides cash from operations by net income. A ratio near or above 1.0 over several years means profit is turning into cash. Compare it with the company's history and peers.
Can AI analyze a cash flow statement?
Yes. AI tools can read statements from Excel or PDF, calculate free cash flow and cash conversion, and flag large changes between years. Powerdrill Bloom links each figure to its source and can search SEC filings for public companies. Check a few figures by hand.
Sources: US Securities and Exchange Commission, Beginners' Guide to Financial Statements. Details read on October 29, 2026.