How to Make a Budget in Excel: Step by Step
To make a budget in Excel, list your income and expense categories in column A. Put planned amounts in column B and actual amounts in column C. Total each section with the SUM function, then subtract total expenses from total income. Add a column for the difference between planned and actual, so you can see where spending ran over.
This guide covers how to gather your numbers, set up the sheet, and total spending by category with SUM and SUMIF. It also walks through a full monthly example and a faster way to build the sheet from bank exports. Steps come from Microsoft's support pages and the Consumer Financial Protection Bureau's budgeting guide, read on November 16, 2026.
What a budget in Excel does
A budget is a plan for your money over a period, usually a month. It compares what comes in with what goes out, and it shows what is left to save.
The Consumer Financial Protection Bureau (CFPB) explains why a budget matters. Until you see "how much money you're bringing in and where it's going," it is hard to plan. The guide says that without this picture, "it's difficult to know whether you'll have enough left over to put away."
Excel is a good tool for a budget. It adds up totals for you, updates them when a number changes, and keeps a record month after month. A template can work, but building your own sheet helps you understand every number in it.
The same approach works for a household, a small business, a club, or a project. Only the categories change.
Gather your numbers first
Before you open Excel, collect the facts your budget will rest on. The CFPB's guide breaks this into clear questions.
- Where does my money come from? The guide says to start "getting a complete picture of where your money comes from." Include salary, side income, and any benefits.
- Where does my money go? The guide calls logging spending "the heaviest lift." Look at bank and card statements for the last one to three months.
- What are my bills and when are they due? The guide notes that a shortfall "could be that the timing for your bills and income don't match."
If tracking feels overwhelming, the CFPB suggests starting small. You can "look at your expenses one week at a time by either reviewing your receipts or checking account."
Group your spending into categories. Common ones are housing, utilities, groceries, transport, insurance, phone and internet, eating out, entertainment, savings, and debt payments. Ten to fifteen categories is a manageable number.
Set up the sheet
A clear layout makes the budget easy to read and update. Start with a blank workbook and set up these columns:
| Column | What goes in it |
|---|---|
| A | Category name |
| B | Planned amount |
| C | Actual amount |
| D | Difference (actual minus planned) |
| E | Notes |
Put income at the top, in its own section. Put expenses below, with one row per category. Leave a row under each section for its total.
Turn each section into an Excel table. Microsoft says you can "turn a range of cells into an Excel table" to make data easier to manage. To do it, select the range, then select Home > Format as Table and pick a style. Check the box for headers if the first row holds your column names.
Tables bring two helpful features. Banded rows make long lists easier to read. A total row gives you an AutoSum list with functions "such as SUM, AVERAGE, and so on."
Format the amount columns as currency. Select the cells, then choose Currency from the number format list on the Home tab. This keeps every amount readable.
Add categories with a drop-down list
If you also keep a log of individual purchases, use a drop-down list for the category. It stops typos such as "Grocery" in one row and "Groceries" in another, which would break your totals.
Microsoft's steps are short:
- Type your category names on a separate sheet. Ideally, put them in an Excel table.
- Select the cell where you want the drop-down list.
- Go to the Data tab, and then select Data Validation.
- On the Settings tab, in the Allow box, select List.
- In the Source box, select your list of categories.
- Check the In-cell dropdown box.
The table step matters. Microsoft explains the benefit of a table. As you add or remove items, "any drop-downs you based on that table will automatically update."
You can also add an error alert. It shows a message when someone types a category that is not on the list.
Total income and spending with SUM
The SUM function does most of the work. Microsoft describes it simply: "The SUM function adds values."
The syntax is SUM(number1,[number2],...). For example, if your planned expenses are in B12 to B21, type this in the total row:
=SUM(B12:B21)
Do the same for the actual column, and for income. Then find what is left over:
=B8-B22
Here B8 is total planned income and B22 is total planned expenses. Copy the formula across to get the leftover amount for actual figures too.
Microsoft also warns against adding cells one by one. Formulas like =A1+B1+C1 can break when a cell holds text. Its page says these produce "#VALUE! errors from referencing text instead of numbers." SUM is safer and easier to check.
Total by category with SUMIF
If you log each purchase on its own row, SUMIF turns that log into category totals. Microsoft says "You use the SUMIF function to sum the values in a range that meet criteria that you specify."
The syntax is SUMIF(range, criteria, [sum_range]). Microsoft's own example is =SUMIF(B2:B5, "John", C2:C5). It adds the values in C2:C5 only where the matching cell in B2:B5 equals John.
For a spending log, the categories might be in column B and the amounts in column C. To total groceries for the month, use:
=SUMIF(B2:B60, "Groceries", C2:C60)
Better still, point the criteria to the category name in your summary sheet. Then one formula can be copied down for every category. Note that text criteria must be "enclosed in double quotation marks," unless you use a cell reference.
To total by two conditions, such as category and month, use SUMIFS instead.
Track actuals and the difference
A budget is only useful if you compare it with what really happened. Fill in the actual column at the end of each month, or each week if you prefer.
In column D, subtract planned from actual:
=C12-B12
A positive number means you spent more than planned. A negative number means you spent less. Copy the formula down for every category.
To make overspending stand out, add conditional formatting. Select column D, then select Home > Conditional Formatting > Highlight Cells Rules > Greater Than. Enter 0 and pick a red fill.
Keep one budget sheet per month in the same workbook. Name each tab with the month, such as "2026-11." This makes it easy to compare months and spot patterns.
A monthly budget example
Here is a simple example for one household in November 2026. All amounts are in US dollars.
Income:
| Category | Planned | Actual |
|---|---|---|
| Salary | 4,200 | 4,200 |
| Side job | 600 | 600 |
| Total income | 4,800 | 4,800 |
Expenses:
| Category | Planned | Actual | Difference |
|---|---|---|---|
| Rent | 1,500 | 1,500 | 0 |
| Utilities | 220 | 245 | 25 |
| Groceries | 600 | 680 | 80 |
| Transport | 250 | 230 | -20 |
| Insurance | 180 | 180 | 0 |
| Phone and internet | 120 | 120 | 0 |
| Eating out | 200 | 310 | 110 |
| Entertainment | 150 | 140 | -10 |
| Savings | 800 | 800 | 0 |
| Debt payment | 400 | 400 | 0 |
| Total expenses | 4,420 | 4,605 | 185 |
The planned total is =SUM(B12:B21), which gives 4,420. The actual total is 4,605. The difference column adds up to 185, which matches 4,605 minus 4,420.
The leftover amount was 380 in the plan. In practice it was 195. The difference column shows why: eating out ran 110 over, and groceries ran 80 over.
That points to a clear next step. Next month, either raise the groceries line to match reality or set a weekly grocery limit. Eating out is the easier place to cut.
Plan ahead and stick to your budget
Monthly bills are easy to plan. Costs that arrive once or twice a year are not. Car repairs, annual insurance, gifts, and school fees can wreck a month that looked fine on paper.
The fix is to spread them out. Add up your irregular costs for the year and divide by twelve. Put that amount in a category such as "Annual costs" and set it aside each month. When the bill arrives, the money is already there.
Treat savings the same way. Put savings near the top of the expense list, not at the bottom. A goal such as an emergency fund then gets paid first, instead of from whatever is left.
You can track progress in the same workbook. Add a small table with each goal, the target amount, and the amount saved so far. A simple formula such as =C3/B3 shows the share of each goal reached. Format it as a percentage.
Building the sheet is the easy part. Using it every month is harder. The CFPB's guide offers a few practical tips.
- Make it work for you. The guide says to "Create a tool that works for you" and to look at your finances "one month at a time."
- Review your habits. It calls this "the easiest way to look for areas where you can cut back."
- Set a goal. A clear target, small or large, gives the effort a purpose.
- Find support. The guide compares it to an exercise routine. It is easier with "families and friends you can trust."
A short monthly review helps the habit stick. Pick a fixed day, fill in the actuals, and read the difference column. Ten minutes is usually enough.
Make a budget in Excel with AI
When your spending lives in months of bank exports, sorting every row into categories takes time. An AI tool can read the files and build the summary for you.
Here is the method in three steps, using Powerdrill Bloom.
Step 1: Upload your bank or card exports
Upload your transaction exports as Excel, CSV, or PDF files. For a business, upload the planned figures and the actuals from your accounting system. The AI Budget Analysis Tool lists "Excel, CSV or PDF exports from accounting and FP&A" as inputs.
Include at least one full month. Two or three months give a better picture of normal spending.
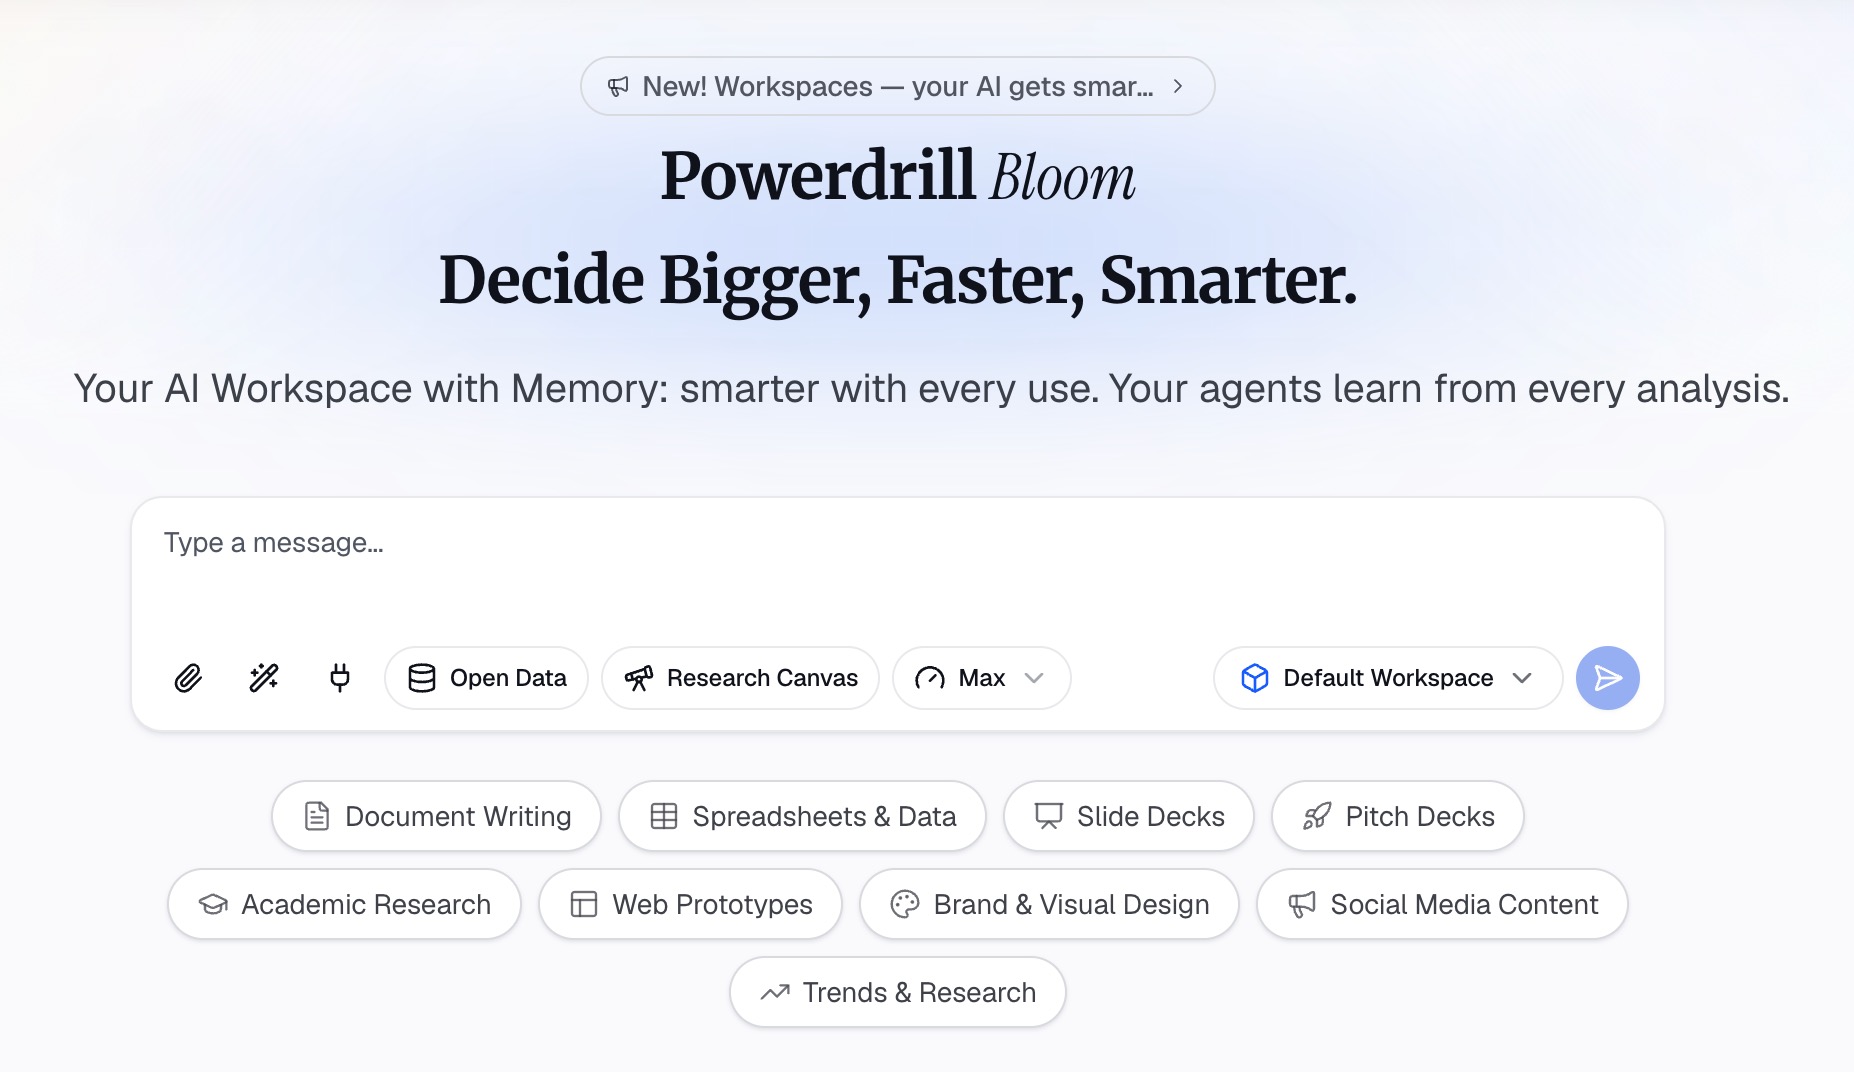
Step 2: Ask for the budget summary in natural language
Describe the output you need. For example: "Group these transactions into categories, total each one by month, and compare them with my planned amounts."
The tool page says you can "Compare budget vs actual, surface variances with driver explanations and a clean reforecast." You can also ask for a chart of spending by category.
Step 3: Check the totals and export the workbook
Check the category totals against your statements. Move any transaction the AI placed in the wrong category. Then export the results.
The tool page lists a "Reforecast workbook with original budget, YTD actuals and revised year-end" among its outputs. Open it in Excel and keep updating it with the formulas above.
Common mistakes to avoid
These are the problems that come up most often when people build a budget in Excel.
- Guessing instead of checking. Use real statements, not memory, for your first plan.
- Too many categories. Fifty lines are hard to track. Start with ten to fifteen.
- Inconsistent category names. Use a drop-down list so SUMIF totals stay correct.
- Adding cells one by one. Use SUM ranges instead of long chains of plus signs.
- No actual column. A plan without actuals never shows where it went wrong.
- Forgetting irregular bills. Spread annual costs, such as insurance, across twelve months.
- Never updating it. The CFPB says to update your plan "if you experience a change in employment or your spending habits."
- No review day. Without a fixed day each month, the sheet falls out of date.
For a business version, see our guide on how to build a budget vs. actual report. For the reporting side, see our guide on how to analyze an income statement.
When you are ready to turn your statements into a working plan, try Powerdrill Bloom with last month's bank export.
Frequently asked questions
How do I make a simple budget in Excel?
List income and expense categories in column A, planned amounts in column B, and actual amounts in column C. Total each section with SUM, and subtract total expenses from total income to see what is left.
What formulas do I need for a budget in Excel?
SUM totals each section. SUMIF totals a transaction log by category. A simple subtraction, such as =C12-B12, shows the difference between actual and planned amounts.
Does Excel have budget templates?
Yes, Excel offers templates, but building your own sheet helps you understand each number. A simple sheet with the columns in this guide is enough for most households.
How do I track spending by category in Excel?
Log each purchase with a category from a drop-down list. Then use SUMIF to total the amounts for each category. Use SUMIFS to total by category and month.
How often should I update my budget?
Update the actual amounts at least once a month, or weekly if money is tight. The CFPB also suggests updating the plan when your job or spending habits change.
Sources: CFPB, Budgeting: How to create a budget and stick with it · Microsoft Support, SUM function · Microsoft Support, SUMIF function · Microsoft Support, Create a drop-down list · Microsoft Support, Overview of Excel tables.